






A target is not the same as a launch list
Circle has described the scale and regions of its ambition, but it has not published a final list of forty countries or one deadline covering them all. Each market has different licensing, banking and consumer-protection rules. USDC has not already entered every target market.
The rollout is more likely to happen through separate local relationships and approvals. Some markets may support direct institutional access, while others depend on licensed exchanges, payment processors or banking partners. Availability for a global company does not automatically mean the same product is open to every retail user.
Payments are the clearest commercial argument
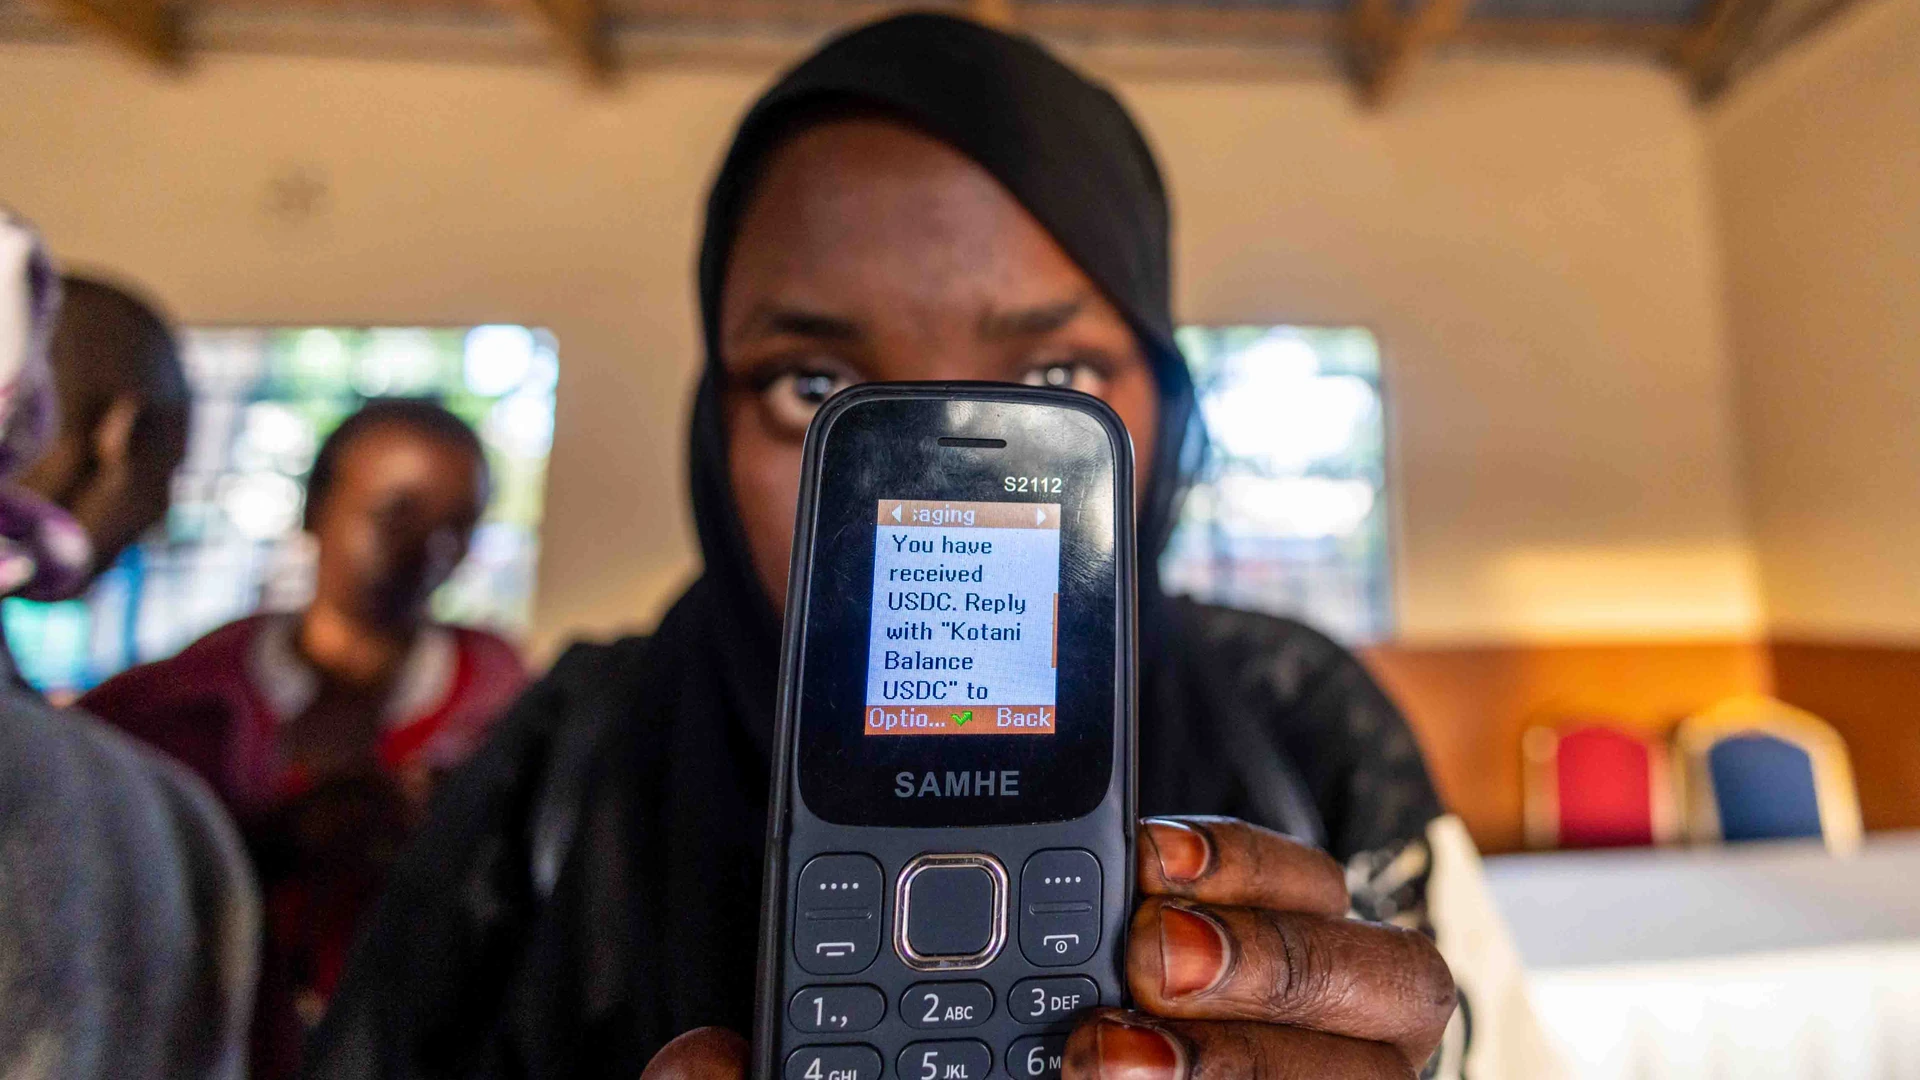
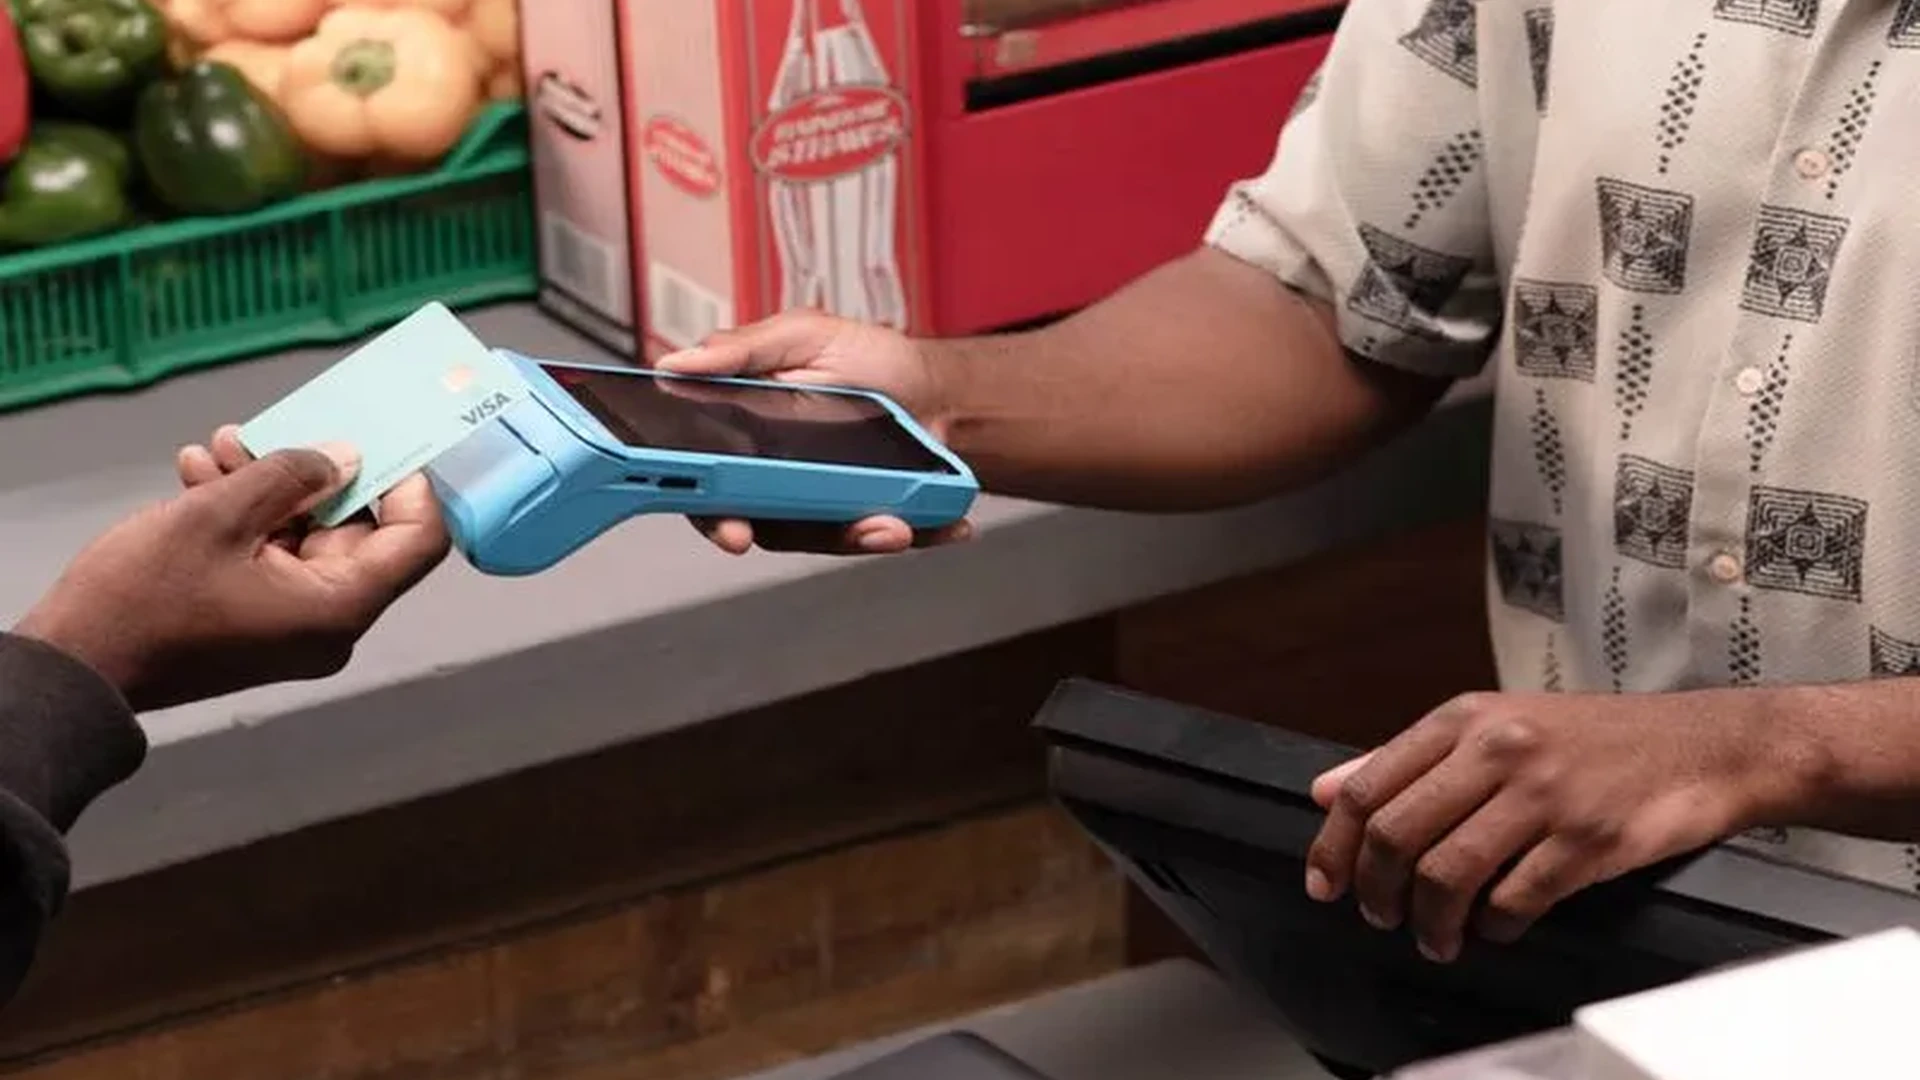
Stablecoins can reduce the time between sending value and making it usable, particularly across borders and outside banking hours. For payment firms, the benefit is not that a token removes every intermediary. It is that settlement can occur on a common network while local partners handle compliance and conversion at each end.
That model still has costs. Liquidity, on- and off-ramp fees, foreign-exchange spreads and local reporting can determine whether a stablecoin route is cheaper than an existing system. A useful pilot measures the complete transaction rather than advertising only the low network fee in the middle.
Banks and regulators will determine the pace
Circle needs reserve confidence and local access at the same time. Banks may value programmable settlement but require clear ownership, redemption and sanctions controls. Regulators may permit institutional use before opening broader consumer distribution. Those decisions are market-specific and can move at different speeds even inside one region.
Users should therefore verify the licensed provider, redemption route and applicable limits in their own jurisdiction. The announcement signals where Circle wants to grow; it does not replace local terms or guarantee that an account can be opened today.
The next evidence will be named partnerships
The strongest proof of progress will be country-specific approvals, banking integrations and payment volumes rather than another large geographic number. Named partners can show how dollars enter and leave the system, who handles customer checks and what happens when a transfer fails.
Circle’s plan is significant because forty markets could broaden stablecoin use beyond trading. Much of the work remains ahead, and the completed footprint is still smaller than the target.
Denne artikel er kun til information og er ikke investeringsrådgivning.
 admin_wcContributor · World-CryptMore from