The Hong Kong government has introduced a bill designed to extend virtual-asset regulation beyond the services already covered. The proposal targets four areas: trading, advisory work, asset management and custody. Businesses operating in those fields would need a licence or registration rather than relying on a gap between older financial rules and newer digital products.
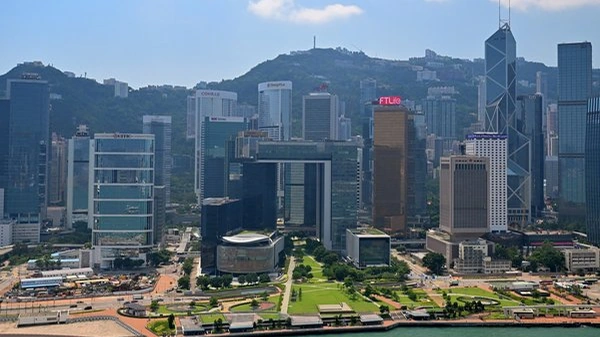
The bill follows the principle that similar activities and risks should face similar regulation. That approach matters because custody and advice can expose customers to financial losses even when no crypto exchange is directly involved. Clear responsibility may raise compliance costs, but it also defines who must protect assets, check clients and report suspicious activity.
The government gazetted the Virtual Asset Services Legislation Amendment Bill on 20 November. It will receive its first reading in the Legislative Council on 2 December. The proposal would amend the Anti-Money Laundering and Counter-Terrorist Financing Ordinance and give the Securities and Futures Commission and Hong Kong Monetary Authority enforcement powers.
Banks would not receive an automatic exemption
Banks and companies licensed to operate stored-value payment services would still need SFC registration if they provide virtual-asset services. That avoids a system in which the same activity faces different standards solely because of the provider’s original licence. Applicants would also need to pass suitability checks and meet other regulatory requirements.
For customers, custody is one of the most important additions. A company that holds digital assets for clients controls access to those assets and must manage private keys, operational security and recovery procedures. A licensing framework cannot remove every technical failure, but it can require governance, audits and clear separation between customer property and the provider’s own balance sheet.
The market gains clearer rules, not unrestricted approval
Hong Kong is presenting the bill as a way to support responsible innovation while strengthening investor protection. That balance means firms receive a defined compliance route, but cannot treat the jurisdiction as permission to launch any product without oversight. Smaller providers may need to reconsider whether they can meet capital, staffing and control requirements.
The proposal does not guarantee faster growth in digital assets, and final rules may change during the legislative process. Its immediate importance is structural: trading, advice, management and custody would sit within one clearer regulatory system. If implemented well, the regime could reduce uncertainty for serious firms while making it harder for poorly controlled operators to present themselves as equally reliable providers.
This article is for information only and is not investment advice.
 admin_wcContributor · World-CryptMore from