A clean audit opinion means that the auditor found no material problems in the financial statements under the relevant accounting rules. It does not remove every market or operational risk, but it provides stronger evidence than a management statement alone.
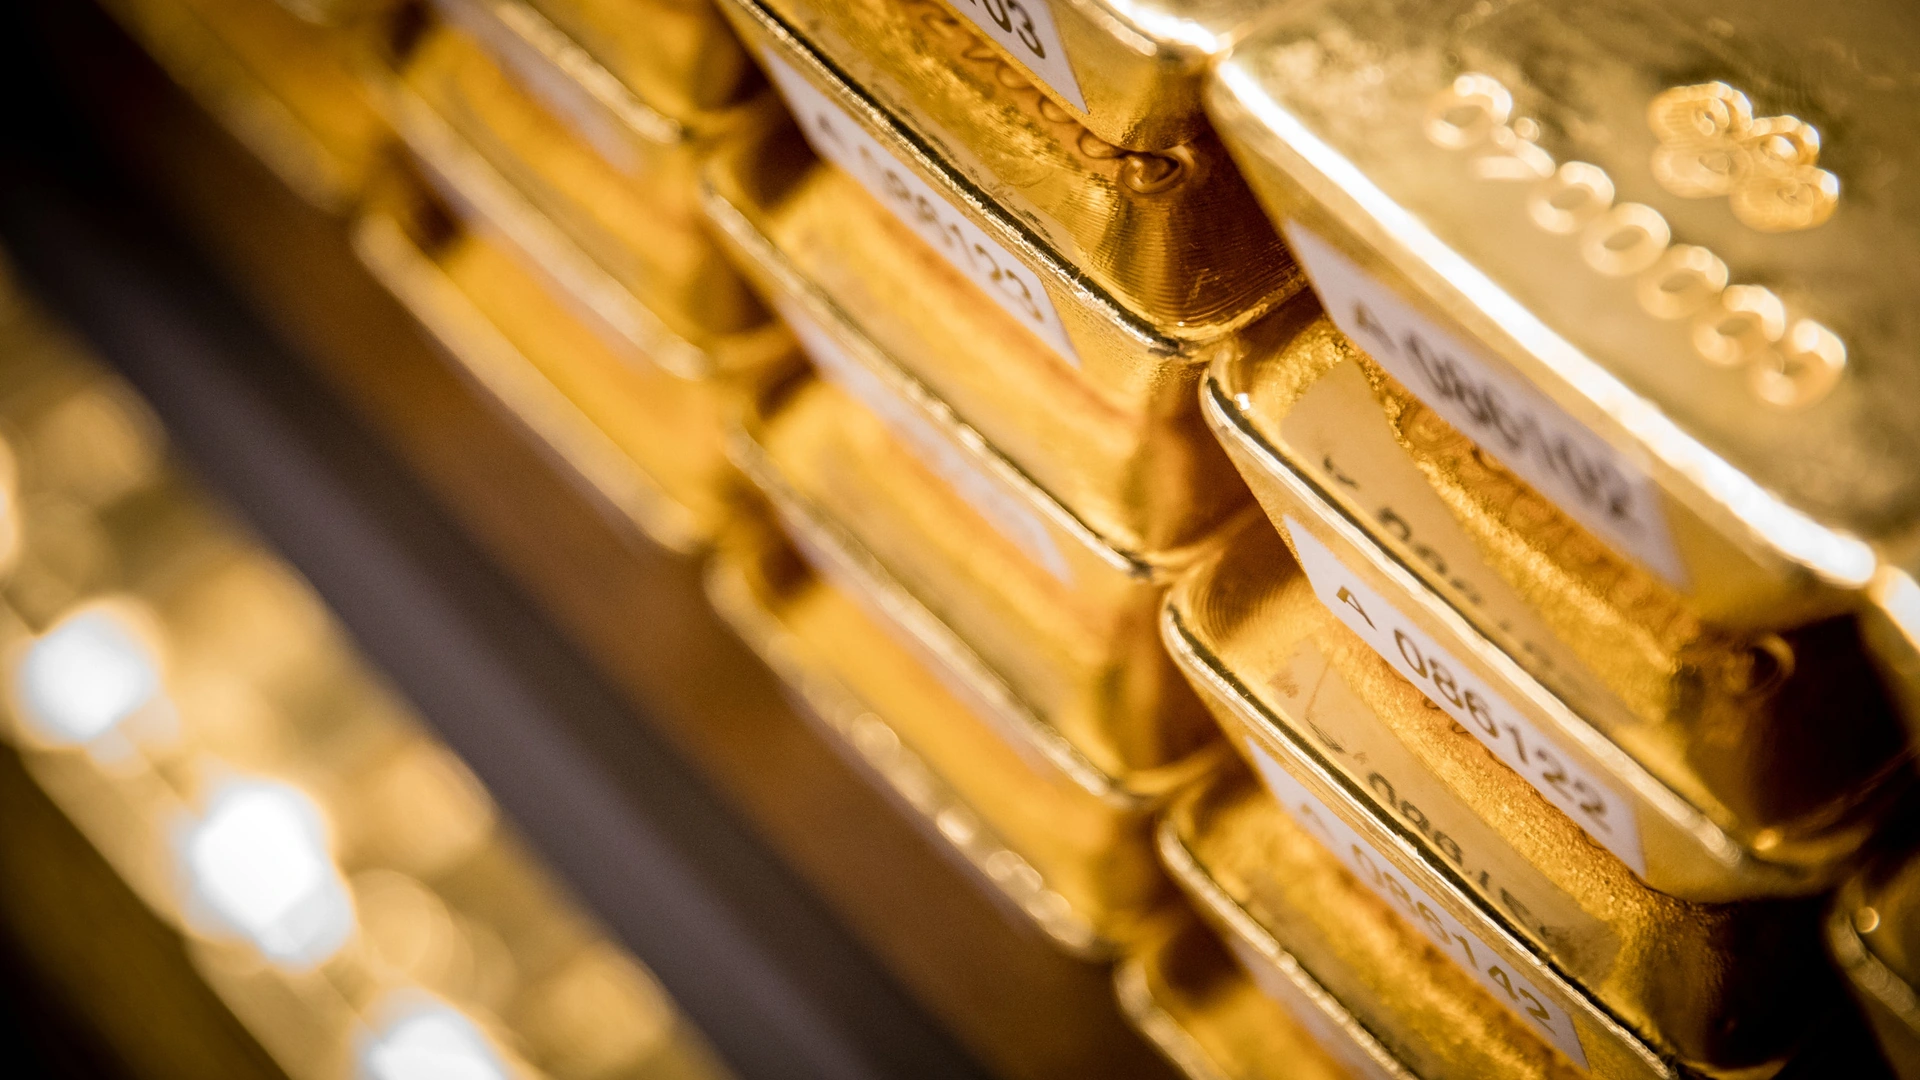
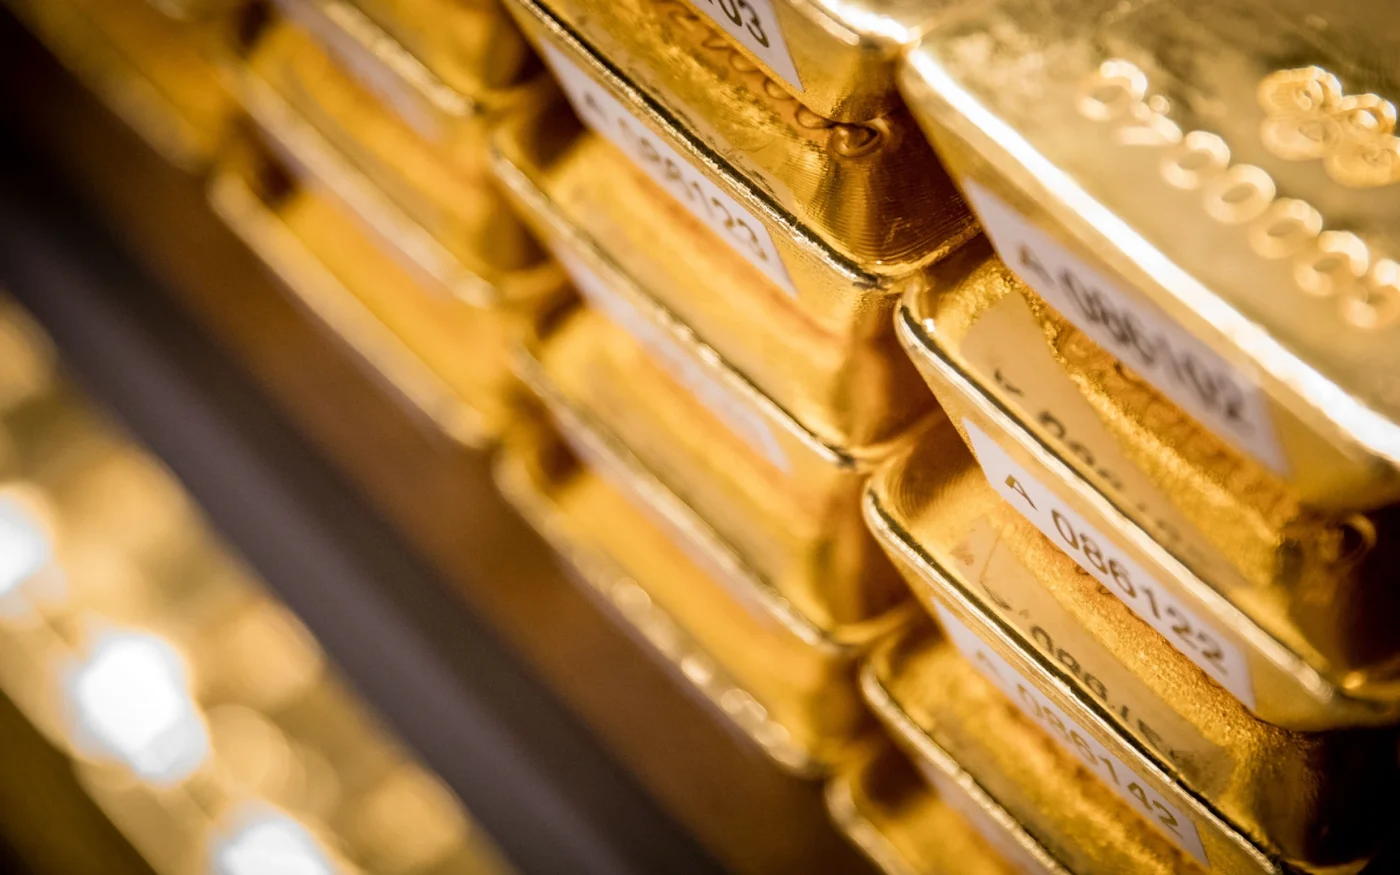
Tether announced the result on 12 November. The audited period ended on 31 December 2025. KPMG counted and inspected individual gold bars rather than relying only on confirmations from a storage provider.
The audit compared token supply with allocated gold
TG Commodities held 520,089.350 fine troy ounces of allocated gold at the end of the audited period. The metal was valued at about 2.246 billion dollars. The reported token supply was 520,089.300 XAUt.
Each XAUt token represents an undivided ownership interest in gold on specified bars. Tether says the metal is stored in Swiss vaults and meets London Good Delivery standards. Token holders can use the company’s systems to identify the bars connected to their holdings.
| Audited item | Reported figure |
|---|---|
| Fine troy ounces of gold | 520,089.350 |
| Value of gold | About $2.246 billion |
| XAUt in issue | 520,089.300 tokens |
| Audit opinion | Clean opinion with no material problems identified |
| Auditor | KPMG US |
Physical inspection adds a separate layer of assurance
The physical count matters because tokenised gold depends on the existence and identification of real metal. KPMG checked the bars and their identifying information. Management also uses a qualified independent party to test a sample each quarter.
The audit follows a separate KPMG opinion on Tether International, the issuer of USDt. Tether presents the two reports as part of a broader move towards full financial statement audits across its businesses.
Investors should still distinguish between an audit of historical statements and a guarantee of future liquidity or price. XAUt follows the value of gold, and its market price can also reflect trading conditions on individual platforms.
For the tokenised-asset sector, the report raises the standard of evidence expected from issuers. Claims about reserves are stronger when a recognised external firm checks both records and physical assets.
The next test is whether the company continues to publish comparable audited information for later periods and maintains a clear link between token supply and allocated gold.
This article is for information only and is not investment advice.
 admin_wcContributor · World-CryptMore from